Draft preview for Bryan's review · Not published · All pages

You served. Let's make
sure you understand
your VA home loan
and use it well.
Bryan Hernandez
Bryan Hernandez

Straight answers for Colorado service members, veterans,
Reservists, Guard members, and military families, from a
Denver loan officer who is also a U.S. Army Sergeant.

The VA home loan is one of the most talked-about parts of
military life, and one of the most misunderstood. Whether you're
PCSing, buying your first home, or wondering whether a refinance
makes sense, you deserve a plan built on facts, not barracks
rumors. Tell me where you are, and we'll work out your next step
together.

Takes about a minute. Only phone and email are required. Add your branch and buying stage so our first conversation is more useful.

REVIEW Review note: the live GHL form below shows its current fields and a "Submit" button until it is updated in GHL.
Suggested button label: Talk Through My VA Options ↗

What you'll get

Certificate of Eligibility (COE)

Help understanding the Certificate of Eligibility (COE): what it is, how to request it, and where it fits in the process

02

Pre-approval to closing

A clear walkthrough of the steps from pre-approval to closing, including the VA appraisal, so nothing catches you off guard

03

Honest loan comparison

An honest comparison with other loan options when a different path makes more sense for you

04

What happens after you submit

  1. I review your details personally.

    Your branch and buying stage tell me where to start. No call center, no hand-offs.

  2. I reach out within one business day.

    We set a short call at a time that works around duty, drill weekends, or work.

  3. You leave with clear next steps.

    What to gather, what to expect, and what it means for your timeline, whether you’re buying this month or next year.
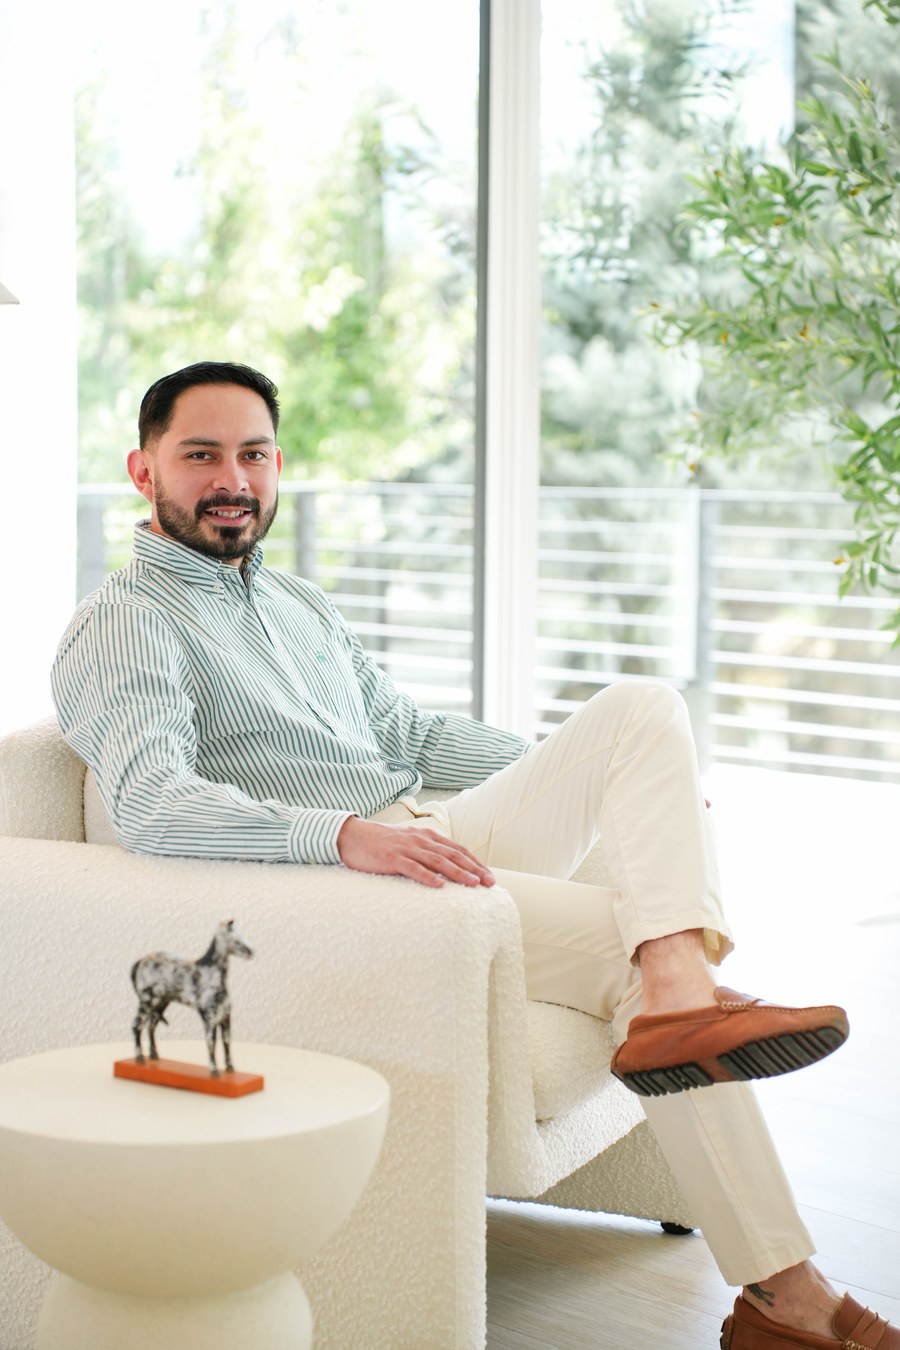
Bryan Hernandez
Bryan Hernandez Lendi Financial · NMLS #2549961

Why Bryan

More Than a Loan Officer. A Partner in Your Homeownership Journey.

Buying a home is more than a financial transaction—it's a major milestone, and you deserve someone who understands what's at stake.

With over 10 years of experience in construction, real estate, and project management, I bring a unique perspective to mortgage lending. As a U.S. Army Sergeant, I understand the importance of integrity, accountability, and delivering on commitments.

Whether you're purchasing your first home, using your VA benefits, investing in real estate, or exploring financing options, my mission is simple: provide honest guidance, clear communication, and mortgage solutions tailored to your goals.

Based in Denver, licensed in Colorado, and fluent in English and Spanish, I'm committed to making homeownership more accessible, understandable, and achievable.

Military service is part of my personal background and does not imply endorsement by the U.S. Army, Department of Defense, or VA.

FAQ

No. Lendi Financial is a private mortgage company. I help you understand and use your VA home loan option, but I don't represent the VA or any government agency.
• VA Loan Questions
Yes, in many cases. National Guard members can become eligible for a VA home loan by meeting the service requirements, which depend on factors like your time in service and type of service. We'll review your service history together and request your Certificate of Eligibility to confirm.
Yes. Active-duty service members can use the VA home loan benefit once they meet the minimum service requirement. Timing around a PCS move or deployment matters, so we'll plan around your orders.
The COE is the document that confirms to a lender that you're eligible for the VA home loan benefit, and it shows your available entitlement. I can help you request it, so you don't have to chase the paperwork on your own.
Possibly. The VA doesn't set an official minimum credit score, but lenders set their own standards, and some may consider a score around 580 depending on your full file: income, debts, and credit history. I can't promise an outcome before reviewing your situation, but I'll tell you honestly where you stand and what could strengthen your file. VERIFY: credit-score answer
No. VA loans don't require monthly private mortgage insurance (PMI). Most VA borrowers pay a one-time VA funding fee instead, unless they're exempt.
Yes. A VA loan can be used to buy a property with up to four units, including a duplex, as long as you live in one of the units as your primary residence. We'll walk through what that means for your purchase and your plans.
Generally, no. A VA loan is meant for the home you'll live in as your primary residence, so a vacation or second home usually doesn't qualify. If you're moving and want to keep your current home, buying a new primary residence with a VA loan may still be possible depending on your remaining entitlement, and we can look at that together. VERIFY: second-home answer
The VA funding fee is a one-time fee paid on most VA loans. The amount varies based on your type of service, whether it's your first time using the benefit, and your down payment, and it can usually be financed into the loan. Veterans who receive VA disability compensation are generally exempt. VERIFY: funding-fee answer
• Frequently Asked Questions About Home Loans
The amount you need depends on your loan program, purchase price, and eligibility. Some VA and USDA loans offer 0% down payment options, FHA loans may allow as little as 3.5% down, and certain conventional loans allow 3% down. Down payment assistance programs may also help eligible Colorado homebuyers reduce upfront costs.
Credit score requirements vary by loan type, lender, and your overall financial profile. Some mortgage programs offer flexibility for borrowers with less-than-perfect credit. I'll help you understand your financing options and identify the next steps toward qualifying.
Yes, certain qualified borrowers may purchase a home with no down payment through VA or USDA financing. Other buyers may qualify for down payment assistance programs. Closing costs and other expenses may still apply.
Not at all. I work with first-time homebuyers, military families, real estate investors, self-employed professionals, and buyers from many different backgrounds. Whether you're exploring VA, FHA, conventional, or alternative financing, I'll help you evaluate your options.
FHA loans are government-insured mortgages that may offer more flexible qualification requirements. Conventional loans are not government-insured and may provide different advantages depending on your credit, down payment, and financial goals. The right choice depends on your individual circumstances.
Yes. Self-employed borrowers may qualify using tax returns or, through certain alternative loan programs, eligible bank statements or other income documentation. Qualification depends on the loan program, income history, credit, and other underwriting requirements.
Yes. VA home loan benefits are not necessarily limited to a single use. Depending on your remaining entitlement, existing VA loans, and eligibility, you may be able to use your benefit again.
Yes. Eligible buyers may have access to Colorado Housing and Finance Authority (CHFA) programs and other local homeownership assistance options. Availability, income limits, purchase requirements, and assistance amounts vary by program.
Pre-approval timelines vary depending on your documentation, income, credit profile, and loan program. Having your income records, identification, and financial documents ready can help speed up the review process.
I combine mortgage lending experience with over a decade of construction, real estate, and project management experience, along with my background as a U.S. Army Sergeant. I provide personalized guidance, clear communication, and financing options tailored to your goals. I serve clients in English and Spanish.

Have more questions?

Let's discuss your homeownership goals and find a mortgage solution that works for you.

Schedule a Mortgage Consultation ↗

Takes about a minute. Only phone and email are required.
Add your branch and buying stage so our first
conversation is more useful.

Talk Through My VA Options

Prefer to reach out directly? Email [email protected] or call (720) 309-0534.